
If I’m an Illinois employer, here’s the short answer: ACA reporting for 2026 is a federal IRS job, while Illinois has a separate CCDA disclosure rule. They are not the same thing, and doing one does not satisfy the other.
Here’s what I need to know right away:
- I report 2025 coverage data in 2026
- If I’m an Applicable Large Employer (ALE), I usually file Forms 1094-C and 1095-C
- I must furnish Form 1095-C to employees by March 2, 2026
- I must file with the IRS by March 31, 2026 if filing electronically
- Paper filing is due February 28, 2026 if paper filing is allowed
- The IRS e-filing rule generally applies when I have 10 or more information returns in total
- Illinois also requires a CCDA benefits comparison disclosure at hire, annually, and on request
- A controlled group may need to combine employees across related businesses to test the 50-FTE ALE threshold
In plain English: I need to answer three questions first:
- Am I an ALE based on 2025 data?
- Which forms apply to my plan setup?
- Have I handled both IRS filing and Illinois CCDA disclosure?
A quick example: if I had 42 full-time employees and 960 monthly part-time hours, that equals 50 FTEs under the ACA counting method. That can put me into ALE status even if my year-end headcount looks lower.
The biggest mistake? Treating Illinois ACA compliance like one task. It’s two tracks:
| Requirement | What I do | Main 2026 date |
|---|---|---|
| Federal ACA reporting | File IRS forms for 2025 coverage | March 2, 2026 and March 31, 2026 |
| Illinois CCDA disclosure | Give employees a written benefits comparison | At hire, annually, and on request |
I’d treat this as a filing-and-proof exercise: count employees the right way, use month-by-month records, send forms on time, keep AIR confirmations, and keep records showing CCDA delivery.
Below, I’ll walk through the steps in a simple way.
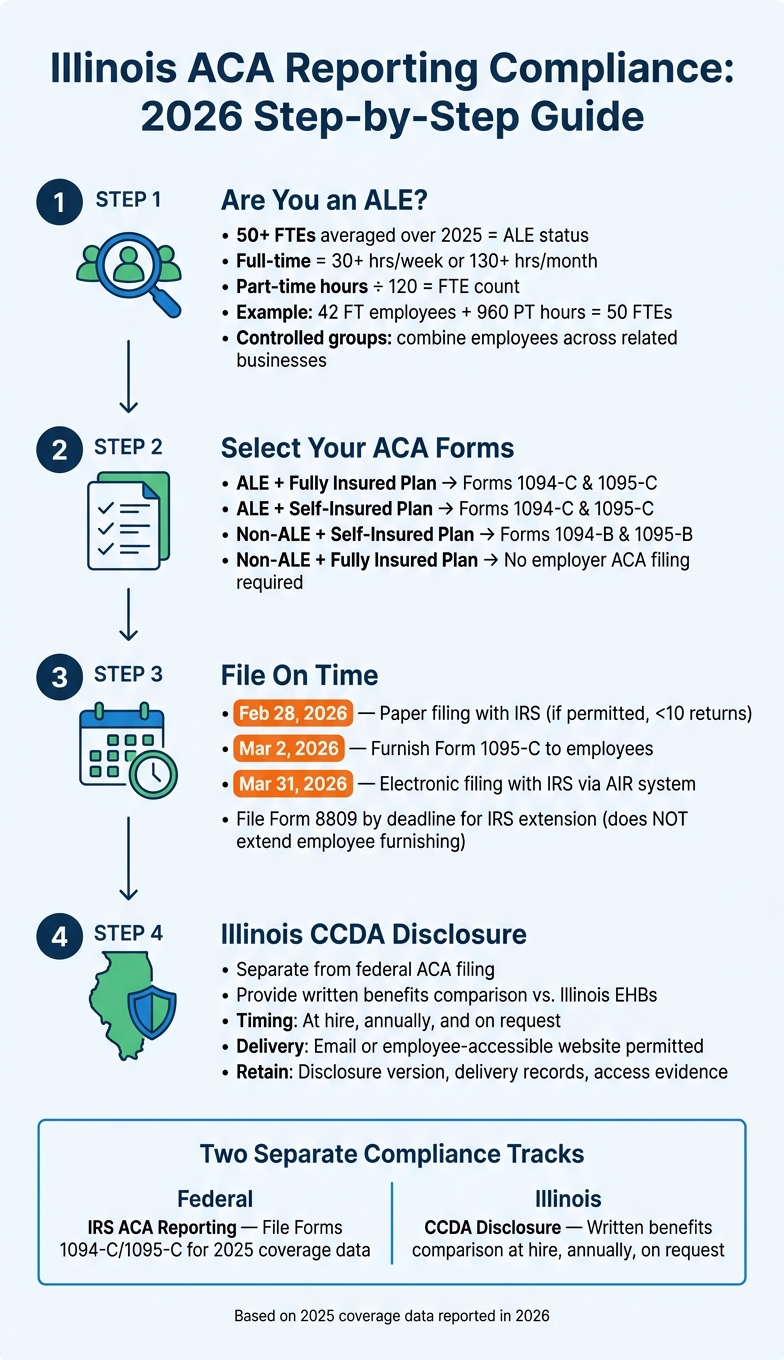
Illinois ACA Reporting Compliance: 2026 Step-by-Step Guide
ACA Refresher: “Play or Pay” and Mandatory Employer Reporting Requirements
Compare group health plans for your Illinois business. Our local, licensed agents shop the top carriers and send you side by side quotes at no cost.
Get Group Quotes
Step 1: Determine Whether Your Illinois Business Must File
Start by figuring out whether your business is an Applicable Large Employer (ALE). That status determines which ACA forms you need to file and what you need to report. If you are an ALE, the next move is pulling together the data for the right forms.
How to Calculate ALE Status Under the ACA
For 2026 reporting, ALE status is based on your 2025 workforce data: not your current headcount. In most cases, an ALE is an employer that averaged at least 50 full-time employees, including full-time equivalents, during 2025.
Here’s how the count works:
- Count each full-time employee. Under the ACA, that means anyone averaging at least 30 hours of service per week or 130 hours per month.
- Then convert non-full-time hours into FTEs. Count up to 120 hours per non-full-time employee per month, divide the total by 120, and add that number to your full-time employee count.
For example, 42 full-time employees plus 960 part-time hours equals 50 FTEs.
Don’t go by your year-end headcount alone. A business that falls below 50 employees by December 31 may still be an ALE if its monthly average during 2025 hit 50 or more.
Controlled-Group and Common-Ownership Rules for Related Businesses
Separate payrolls, EINs, or business locations do not automatically mean separate ACA status. If several Illinois businesses share common ownership or control, such as a parent-subsidiary setup or sister companies, their employees may need to be aggregated to see whether the group passes the 50-employee mark.
That means you should combine commonly controlled businesses before counting employees. After that, each ALE member files its own Form 1094-C. In plain English: count the whole controlled group first, then sort out each entity’s filing duty.
Which Employers Use Forms 1094-C and 1095-C vs. 1094-B and 1095-B
Once ALE status is clear, look at whether the plan is fully insured or self-insured.
| Employer category | Likely forms | Information generally reported |
|---|---|---|
| ALE with a fully insured plan | 1094-C and 1095-C | Monthly offers of coverage and safe-harbor codes |
| ALE with a self-insured plan | 1094-C and 1095-C | Offers of coverage and covered-individual enrollment data |
| Non-ALE with a self-insured plan | 1094-B and 1095-B | Minimum essential coverage and covered-individual enrollment data |
| Non-ALE with a fully insured plan | No employer ACA filing is required solely because of workforce size | The carrier generally handles coverage reporting |
| Multiple ALE members in a controlled group | Separate 1094-C for each ALE member, with 1095-C for that member’s full-time employees | Entity-specific employee and offer-of-coverage data, coordinated across the aggregated group |
A Form 1095-C is generally required for every employee who was full-time for at least one month during the year, even if that employee turned down coverage.
If you’re not sure whether your plan is self-insured, check the funding arrangement with your plan administrator or a qualified compliance professional before choosing your reporting path.
Next, gather the records needed to draft Forms 1094-C and 1095-C.
Step 2: Complete the Right ACA Forms and Gather Your Data
Once you’ve confirmed ALE status, the next step is getting the right records together so you can fill out the forms correctly. ALE status drives two things: which forms you need and which data points you have to report. After that, the work becomes pretty simple in theory, even if it takes some cleanup in practice: pull solid month-by-month source data.
What Forms 1094-C and 1095-C Report
Form 1094-C is the transmittal form sent to the IRS. It’s the employer-level summary. If you file in more than one batch, only one Form 1094-C can be marked as the Authoritative Transmittal.
This form reports whether you offered minimum essential coverage to at least 95% of full-time employees and their dependents, your monthly full-time employee count, your monthly total employee count, and controlled-group details when those apply. It also requires the employer’s nine-digit EIN, not an SSN and not a parent company EIN.
Form 1095-C reports coverage offers for full-time employees. It includes three parts:
- Part I: employer and employee identifying information
- Part II: monthly offer-of-coverage and affordability data, including the employee’s required contribution for the lowest-cost self-only minimum-value plan
- Part III: covered individuals and months of coverage when the employer’s plan is self-insured
Records Employers Need Before Drafting Forms
Don’t build these forms from a year-end payroll snapshot. Use monthly source records.
That usually means pulling payroll registers, timekeeping files, hire dates, termination dates, leave records, benefits eligibility files, enrollment rosters with effective and end dates, offer-of-coverage records, and employee contribution amounts for the lowest-cost self-only minimum-value option. If the plan is self-insured, you’ll also need a dependent enrollment roster that shows each covered individual’s name, identifying information, and coverage months for Part III.
Before filing, reconcile payroll, HR, and benefits data into one master employee list. If those systems don’t match, the forms won’t either.
Common Coding and Data Issues to Catch Early
The messiest problems usually come from mid-year status changes. New hires in waiting periods, terminations, rehires, and employees on unpaid leave are common trouble spots. And a blank month on Form 1095-C doesn’t always mean no coverage. It can point to a missing eligibility code, an unresolved termination date, or a waiting-period entry that never got recorded.
Two mistakes show up again and again.
First, employers sometimes report the employee’s elected deduction instead of the required self-only lowest-cost contribution. Those numbers can be different, especially when the employee picked family coverage.
Second, one annual contribution amount gets used for all 12 months even though plan rates changed midyear. That’s an easy way to bake errors into the form. Monthly rate tables and effective-dated benefit records help stop both problems before filing.
For identity data, run a pre-filing check to catch missing or duplicate Social Security numbers, name mismatches against payroll records, invalid EINs, and employees tied to the wrong ALE member. Clean those up before submission, then move to the 2026 filing deadlines.
Step 3: Meet 2026 Deadlines and File Correctly
Once your data is clean, turn to the two dates that matter most: giving employee statements and filing with the IRS. This step deals with federal timing and transmission only. Illinois disclosure rules come next.
2026 ACA Reporting Deadlines for Employee Forms and IRS Filing
There are three separate obligations on the 2026 calendar, and each one stands on its own. Missing one does not push back the others.
| Requirement | 2026 Deadline | Notes |
|---|---|---|
| Furnish Form 1095-C to employees | March 2, 2026 | Deliver by mail, in person, or electronically with valid consent |
| Paper filing with the IRS (if permitted) | February 28, 2026 | Available only when the employer has fewer than 10 applicable information returns in aggregate |
| Electronic filing with the IRS | March 31, 2026 | Required for most employers that file 10 or more information returns in aggregate |
| Extension request (Form 8809) | By the applicable IRS filing deadline | An IRS filing extension does not extend the employee-furnishing deadline. |
Check current IRS instructions before you file. Dates can move when they fall on a weekend or holiday.
When Electronic Filing Is Required
Electronic filing is required when your aggregate information returns hit 10 or more across all information return types. Do that count early. Write down which return types you included, and don’t rely only on the number from your payroll or benefits system.
Here’s a point that trips people up: ACA forms can’t be sent through the IRS FIRE system. Forms 1094-C and 1095-C must go through the IRS Affordable Care Act Information Returns (AIR) system, either through compatible software or an authorized transmitter.
After you submit, save the AIR submission ID, transmission timestamp, and acceptance confirmation. If a third-party provider handles filing, get written confirmation that spells out:
- What they filed
- Which employees were included
- Who is responsible for rejected files
That last part matters more than it may seem. A rejected file can turn into a scramble if no one owns the fix.
A Year-End Filing Workflow from Review to Submission
Start with the same monthly records from Step 2, then shift from cleanup to filing control.
Reconfirm ALE status, controlled-group structure, and filing entities. Recheck the full-time employee list. Validate monthly offer codes, employee contributions, and safe-harbor entries. Confirm mailing addresses and electronic consent. Then calculate your aggregate return count and file by the right deadline.
Set your own internal due dates earlier than the IRS deadlines. Finish data validation several weeks before March 2. Leave time for provider testing, address fixes, and rejected-file cleanup if something goes sideways.
Furnish Forms 1095-C to employees by March 2, then submit Forms 1094-C and 1095-C through AIR by March 31 if you are filing electronically. After submission, monitor AIR for rejection notices. A rejected file does not count as filed. Correct the record, resubmit it fast, and keep the rejection notice, corrected file, resubmission ID, and final acceptance confirmation in your compliance records.
After submission, move to Illinois recordkeeping and correction tracking.
Step 4: Illinois-Specific Rules, Recordkeeping, and Corrections
Illinois employers have to handle two separate jobs here: federal ACA reporting and the Illinois CCDA disclosure. In practice, the same employee and coverage data used for ACA reporting can also help document CCDA delivery and any later fixes.
Illinois Consumer Coverage Disclosure Act Requirements
Under the Illinois Consumer Coverage Disclosure Act (CCDA), employers that offer group health insurance to Illinois employees must provide a written comparison of plan benefits with Illinois essential health benefits (EHBs), clearly identifying which EHB categories the plan covers and excludes. This rule applies even if the plan is not otherwise subject to Illinois insurance regulation.
The disclosure must be given at hire, annually, and on request. Many employers send the annual notice during open enrollment. That works well, but it shouldn’t be the only process. You also need a separate way to respond when an employee asks for the disclosure outside that window. Illinois permits delivery by email or through an employee-accessible website.
CCDA compliance is separate from IRS ACA filing.
A simple way to stay organized is to track CCDA delivery in the same compliance file used for ACA reporting. That keeps your records in one place and makes reviews much less messy.
| Requirement | Primary Purpose | Timing | Evidence to Retain |
|---|---|---|---|
| Illinois CCDA Disclosure | Compare employer plan benefits with Illinois-regulated EHBs | At hire, annually, on request | Disclosure version, delivery record, access evidence |
| Form 1095-C | Report offers of coverage to employees and the IRS | Annual employee furnishing and IRS filing deadlines | Furnished copy, filing record, correction history |
| Form 1094-C | Transmit and summarize Forms 1095-C to the IRS | Filed with the employer’s ACA return | Submitted form, IRS confirmation, corrected-transmittal record |
Recordkeeping, Pre-Submission Review, and Correction Tracking
Use a compliance matrix to track both sets of duties. Each row should show the requirement, the department in charge, the employee group covered, the trigger and delivery date, the document kept, and whether someone verified it. Illinois guidance says employers should keep documentation showing that the required information was distributed.
Keep employee counts, hours, offer and enrollment records, CCDA disclosures, filing confirmations, and correction logs. Sort the files by reporting year and plan year. Also, limit access, since these records will include health-plan details and personally identifiable information.
Before you file, have one person prepare the forms and another person review them independently. Give extra attention to records for:
- new hires
- terminated employees
- variable-hour workers
- employees on leave
- employees who changed plans mid-year
Those are the spots where mistakes tend to slip in.
Penalties, IRS Notices, and When to Get Professional Help
If records are incomplete or a filing is wrong, fix it right away and record the change.
Late, missing, or inaccurate ACA forms can lead to federal penalties, with the amount tied to the type of error, when it was fixed, and any relief that may apply. The risk gets higher when the same issue affects many employees or shows up year after year. On the Illinois side, trouble can come from failing to provide the CCDA comparison at hire, annually, or on request, or from not being able to prove that delivery happened.
When a correction is needed, the right fix depends on the mistake. Match the error to the proper correction, log what changed, and keep both the original and corrected records. Your correction log should include the affected employee or filing, the original value, the corrected value, the reason for the fix, the preparer, the reviewer, the submission and furnishing dates, and the final confirmation.
If an IRS notice arrives, calendar the deadline at once and assign one owner to handle it. Then compare the notice against your filed Forms 1094-C and 1095-C, transmission records, payroll data, employee statements, and correction history before deciding whether to accept the IRS position, file corrected information, or send an explanation.
Some notices call for outside help sooner rather than later. That’s often the case when the issue involves multiple employees, repeated reporting years, missing taxpayer identification numbers, controlled-group questions, or a possible assessment. In those cases, prompt review by an ACA reporting specialist, tax professional, benefits counsel, or other qualified adviser makes sense.
For employers that need benefits support, Illinois Health Agents can assist with plan review and enrollment coordination. Employers should still assign clear internal ownership for ACA and CCDA compliance, filing, correction, and recordkeeping.
Conclusion: Key Illinois ACA Reporting Steps for 2027
For 2026, Illinois ACA compliance comes down to a few core tasks: confirm ALE status, file the right federal forms, meet the March 2, 2026 furnishing deadline and the March 31, 2026 electronic filing deadline, and treat CCDA as a separate Illinois requirement.
If errors come up, file corrected forms based on IRS instructions and keep a clear record of what changed and when.
Use the checklist below as a final review before filing.
A Pre-Filing Compliance Checklist
| Checklist Item | Evidence to Retain |
|---|---|
| Confirm ALE status and controlled-group status | Prior-year monthly employee/FTE calculation and entity analysis |
| Select the correct ACA forms | Entity-by-entity form determination |
| Reconcile source data | Reconciled reports and exception review documentation |
| Furnish employee statements by March 2, 2026 | Copies of Forms 1095-C and proof of delivery |
| File with the IRS by February 28, 2026 (paper if permitted) or March 31, 2026 (electronic) | Filed transmittals, confirmations, and any extension records |
| Check whether the 10-return e-filing rule applies | Aggregate return count analysis |
| Complete CCDA disclosures on schedule | Current benefit comparison, delivery records, and request history |
| Correct rejected or inaccurate filings promptly | Correction log, corrected forms, and submission confirmations |
If every item is checked off, the main exposure usually comes down to a filing mistake or a missed disclosure. If controlled-group classification, affordability calculations, or an IRS notice is involved, bring in a qualified tax professional or benefits counsel early. Illinois Health Agents can help coordinate plan information used for ACA and CCDA reporting.
FAQs
How do I know if my business is an ALE?
Your business is an Applicable Large Employer (ALE) if it averaged 50 or more full-time employees, including full-time equivalents (FTEs), during the previous calendar year.
A full-time employee is someone who works at least 30 hours per week or 130 hours per month.
To figure out your FTE count, add:
- Your full-time employees
- Your part-time FTE total
For part-time staff, add up their monthly hours, cap each employee at 120 hours, and then divide the total by 120.
If you own multiple related businesses or businesses under common ownership, you need to combine those employee counts too.
Does Illinois CCDA replace federal ACA filing?
No. Illinois CCDA is a state transparency disclosure rule with its own notice duties. It does not replace federal ACA reporting to the IRS.
Applicable large employers still need to file IRS Forms 1094-C and 1095-C separately from CCDA disclosures.
What should I do if my ACA filing is rejected?
If your ACA filing (Forms 1094-C/1095-C) gets rejected, fix the data errors underneath it and resubmit as soon as you can. The clock doesn’t stop. You still need to meet the annual deadlines: provide copies to employees by March 2 and file electronically with the IRS by March 31.
A lot of rejections happen because of mistakes in employee coverage details. Before you send the forms again, review the basics carefully:
- Employee names
- Addresses
- Monthly coverage status
If you get a state non-compliance notice, respond within 30 days to help avoid penalties.
Recent Comments