
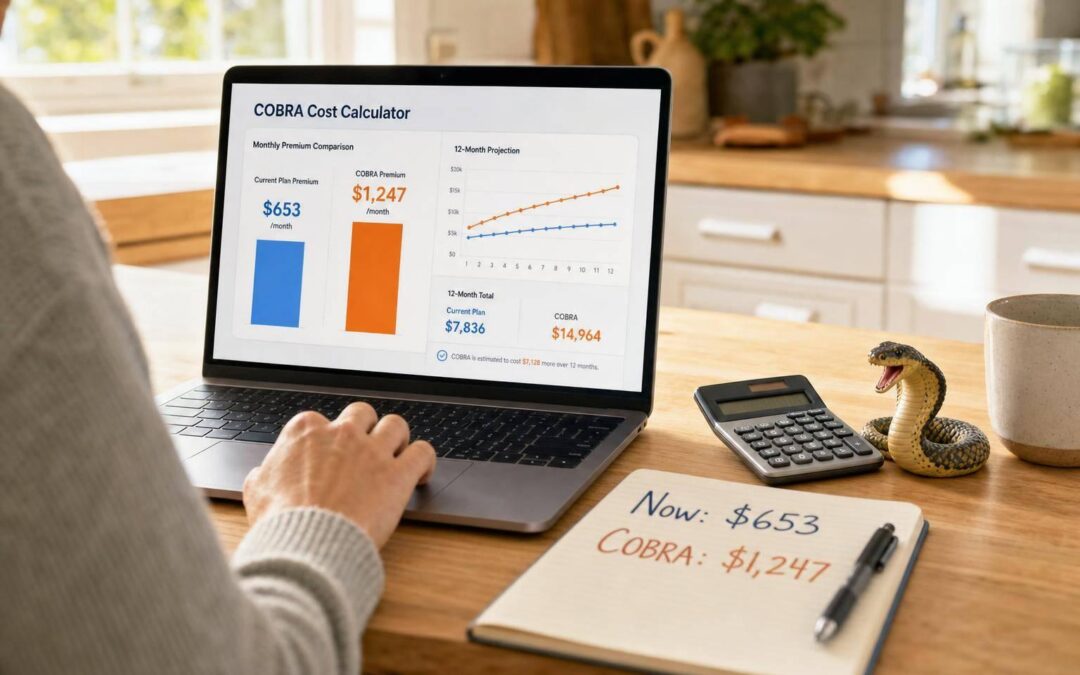
Understand Your Potential COBRA Premium
If you’re leaving a job or losing access to employer-sponsored coverage, one of the first questions is usually simple: what will health insurance cost now? A COBRA cost calculator helps you estimate that jump by combining your current employee premium, your employer’s contribution, and any allowed administrative fee. That gives you a clearer picture of what you may actually owe each month to continue the same plan.
What This Estimate Helps You See
Many people are surprised by how different the monthly bill looks once payroll deductions stop. With a COBRA premium estimate, you can compare what you pay today with the full continuation coverage cost, including optional dental or vision premiums when relevant. That side-by-side view can make budgeting a lot easier.
Important Notes Before You Decide
A calculator can give you a strong starting point, but it can’t replace your official plan notice. Billing methods, coverage options, and eligibility details may vary by employer and administrator. Use this COBRA cost calculator to prepare, ask better questions, and understand the likely increase before enrollment paperwork arrives.
FAQs
How is a COBRA premium usually calculated?
In many cases, COBRA lets you keep the same employer-sponsored health plan, but you may have to pay the full cost yourself. That typically means your current employee share plus the amount your employer was covering, with up to a 2% administrative fee added on top. This calculator follows that common approach so you can get a practical estimate, but your actual bill can vary depending on the plan administrator and how your coverage is structured.
Do dental, vision, HSA, or FSA amounts count toward COBRA costs?
Dental and vision can be included if they are part of the continuation coverage you elect, so this tool lets you add those premiums when needed. HSA or FSA contributions are different. They generally should not be added into the COBRA premium estimate unless your specific plan says they apply. That’s why the calculator treats HSA and FSA amounts as informational comparison fields rather than part of the premium by default.
Why is COBRA so much more expensive than what I paid through payroll?
When you’re employed, your paycheck deduction often reflects only part of the true monthly insurance cost because your employer is paying a significant share behind the scenes. Under COBRA, that employer contribution usually goes away, and you may also see a small administrative fee added. The result is that your monthly payment can feel much higher even though the underlying plan may be the same.
Recent Comments