Estimate Your 1099 Taxes With More Confidence
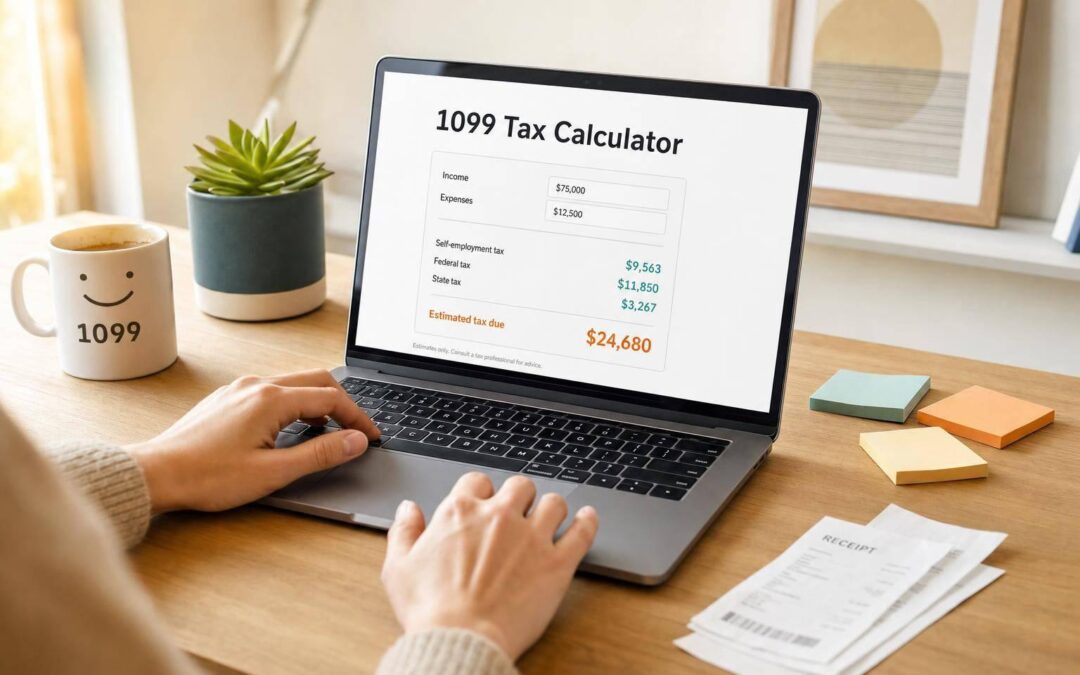
If you earn income as a freelancer, contractor, or sole proprietor, it can be hard to know what to set aside for taxes. A 1099 tax calculator helps you turn rough numbers into a practical estimate by showing how self-employment tax, federal income tax, and optional state tax may add up. That makes it easier to budget for quarterly payments or prepare for tax season without digging through worksheets.
Built for Freelancers and Self-Employed Workers
This tool is designed for people who want a clear, plain-English estimate. You can enter your 1099 income, business expenses, other income, deductions, and any tax payments you’ve already made. The calculator then shows a simple breakdown of net income, taxable income, and estimated taxes in one place.
A Simple Tax Estimate, Not Tax Advice
Because tax rules can get complicated fast, this self-employment tax calculator uses simplified assumptions to keep the process manageable. It can also apply an optional QBI estimate and a flat or custom state tax amount. If you need a quick planning tool, a 1099 tax calculator like this can be a helpful starting point, but your actual return may differ based on credits, itemized deductions, and other tax details.
FAQs
Does this calculator give me an exact tax bill?
No. This tool is designed to give you a simplified estimate, not an exact tax return result. It uses common assumptions for self-employment tax, federal income tax, standard deductions, and an optional state tax estimate. Real tax outcomes can change based on credits, additional income sources, itemized deductions, spouse income, local taxes, and special rules that aren’t included here. Use it for planning, and check with a qualified tax professional or tax software for filing decisions.
How is self-employment tax estimated here?
The calculator starts with your net self-employment income, which is your gross 1099 income minus business expenses, with the result not going below zero. It then applies the standard simplified approach by calculating taxable self-employment earnings at 92.35% of that amount and estimating self-employment tax at 15.3%. If tax-year-specific logic is used, the Social Security portion may be limited by the wage base for that year. Half of the estimated self-employment tax is then treated as a deduction when estimating federal taxable income.
What does the QBI option do, and should I rely on it?
The QBI option applies a simplified version of the qualified business income deduction, typically up to 20% of eligible business income. That can be useful for rough planning, especially if you want a better estimate of your federal taxable income. Still, actual QBI rules can be much more involved and may depend on total income, business type, wage limits, and other factors. It’s a helpful shortcut for estimating, but it shouldn’t be treated as a final determination.
Recent Comments